


"Nvidia Loses Its Captain and 13%, Chip Index Gains 8% — The AI Trade Faces Its Test With 10-Year Yields at 5.15%"
Markets separated "Nvidia risk" from "AI demand" after Jensen Huang's exit, handing the major indexes their first weekly gain in five weeks, even as the 10-year Treasury yield jumped to 5.15%. This week, Nvidia's earnings and Anthropic's IPO will test that optimism.
Last week, Nvidia and the broader AI ecosystem were priced on separate tracks.
Major Index Performance
The S&P 500 rose 2.51% on the week, from 7,376.86 to 7,561.67, while the Nasdaq Composite gained 2.27% to 25,136.27 and the Dow added 2.07% to 52,347.55 (weekly changes calculated from prior-week closes). The S&P 500 and Nasdaq snapped four-week losing streaks, and all three posted their best week since early August[1]. All 11 sectors advanced, led by energy (+5.37%)[2].
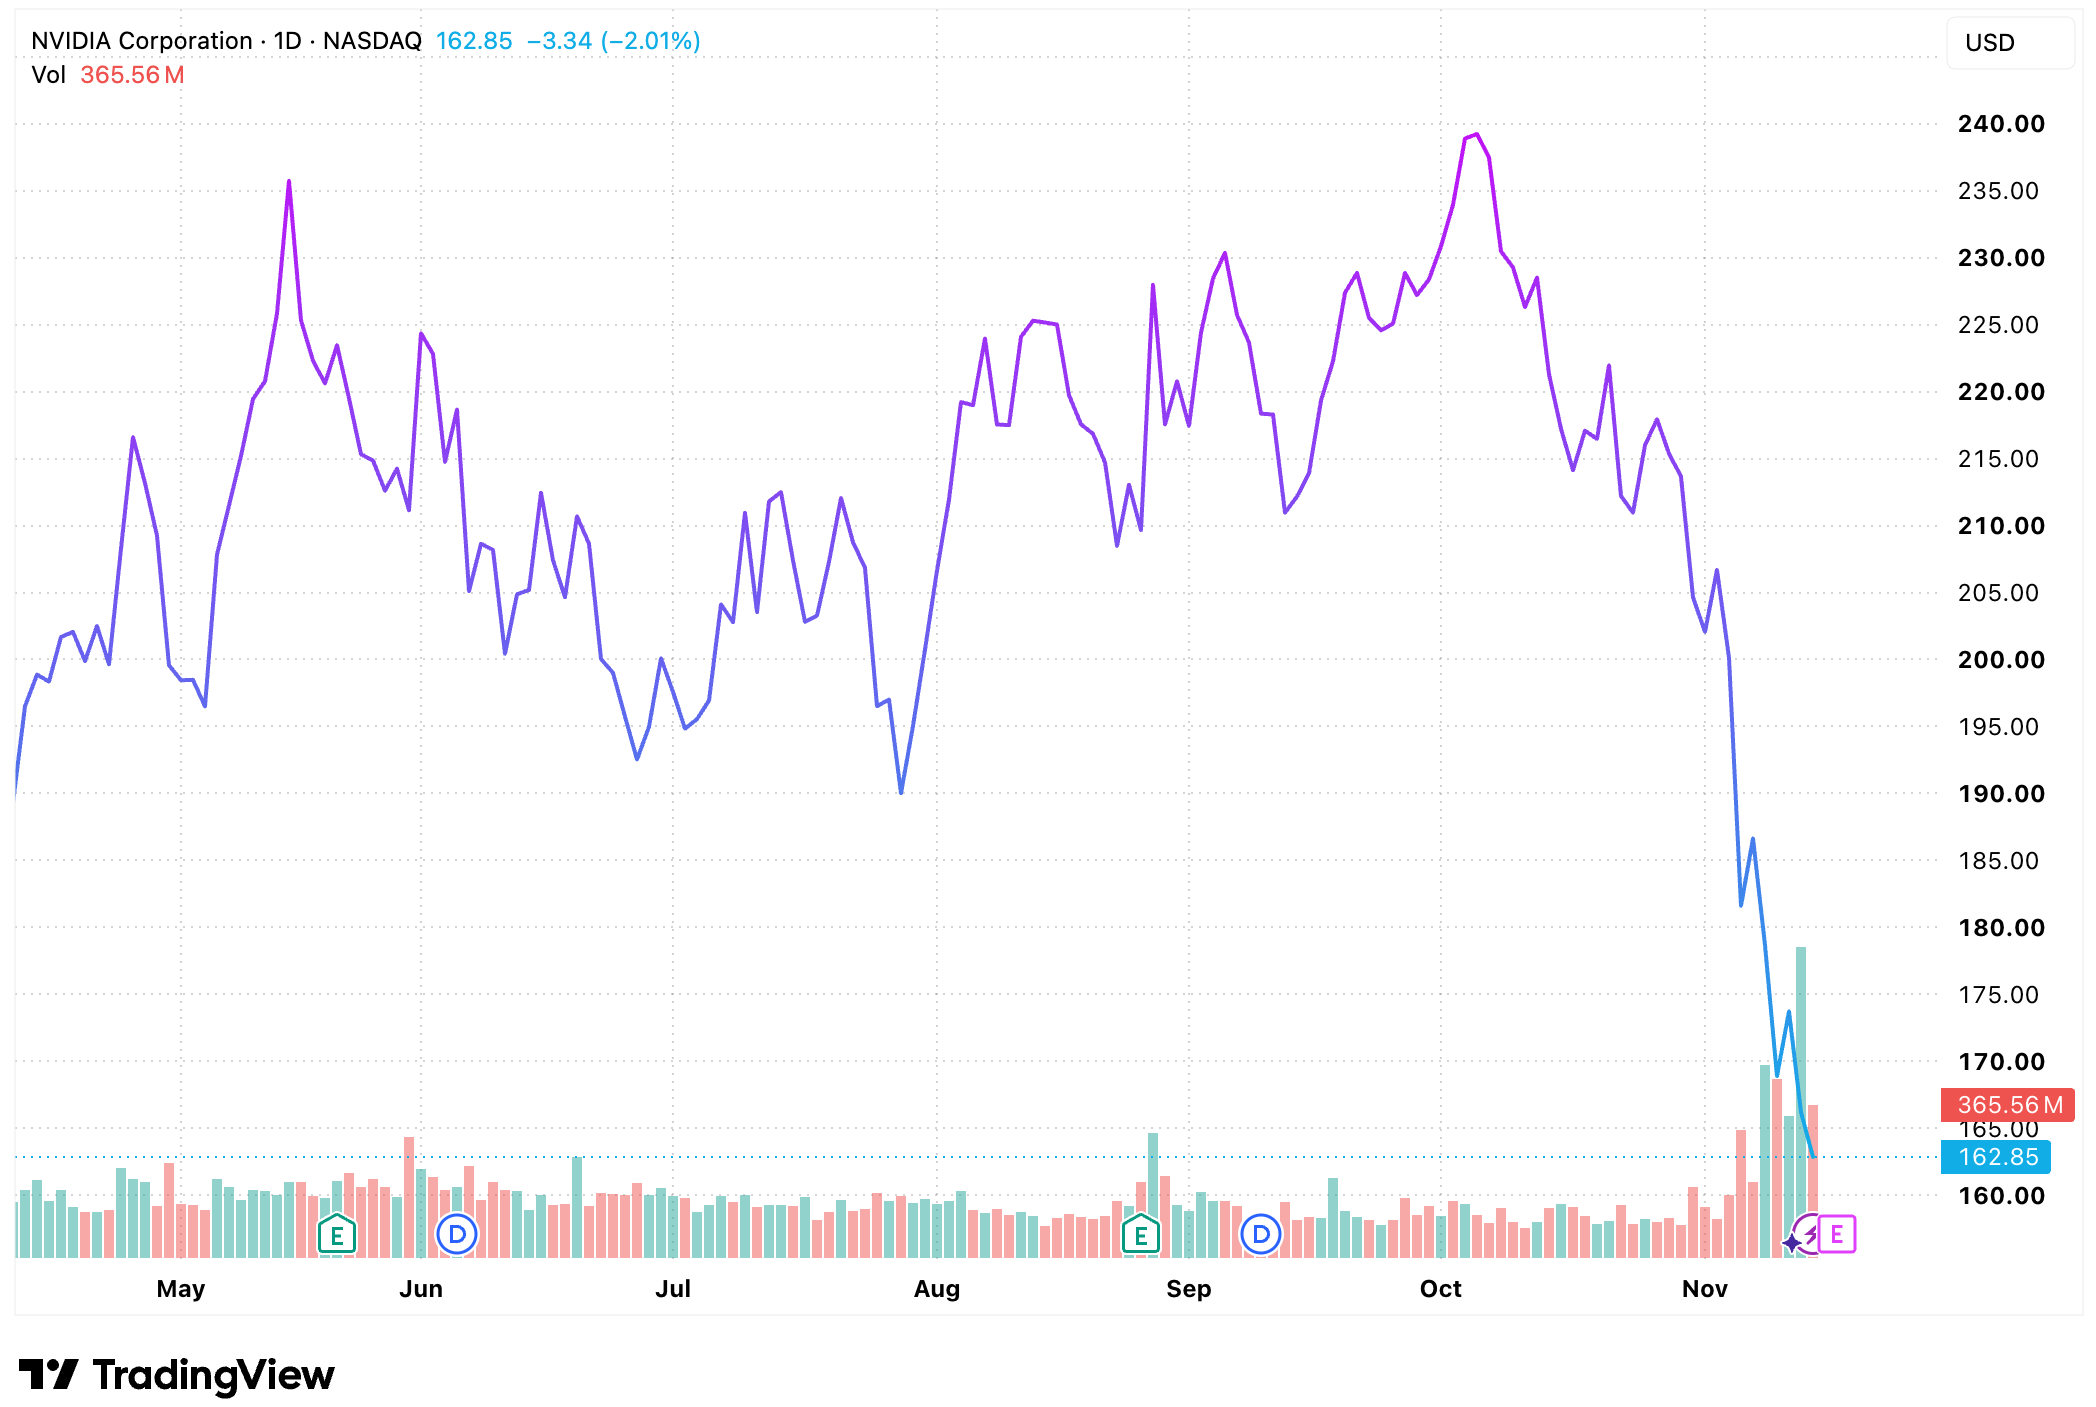
Nvidia was at the center of it all. After a string of reports on Jensen Huang's relationships — one with a person suspected of ties to Chinese intelligence, another with a direct report — the CEO resigned on Thursday, Nov. 12, and CFO Colette Kress was named interim CEO[1]. Nvidia shares fell 13% for the week, a sixth straight weekly decline. Yet the Philadelphia Semiconductor Index (SOX) climbed 8.1%, as bets that rivals would pick up share lifted AMD 18.9% and Broadcom 18.2%[3].
Inflation was the drag. October CPI rose 0.4% m/m and core 0.3%, both above forecasts of 0.3% and 0.2%[3]. No year-over-year figure was published because of the 2025 government shutdown, but KPMG estimates it at about 4.2%[4]. Producer prices released on the 13th were up 6.5% from a year earlier[2].
Korean equities also rebounded. The KOSPI, Korea's main benchmark, slid to 5,018.85 on Nov. 9 — a nine-month low — before closing the week at 5,290.53, up 4.56%, while the tech-heavy KOSDAQ gained 8.60% to 699.66 (calculated directly). On Friday the KOSPI rallied as high as 5,504.44 intraday before reversing, with foreign investors selling a net KRW 703.4 billion that day[5].
Technical Analysis
The SPDR S&P 500 ETF (SPY) briefly cleared its 100-day moving average before stalling near $763 and finishing just below both the 100-day and 20-day lines. With the 20-day still falling, the short-term trend has yet to recover, though the rising 200-day average sits well below the price. First support is seen at $748–750, with resistance at $760–765[3].
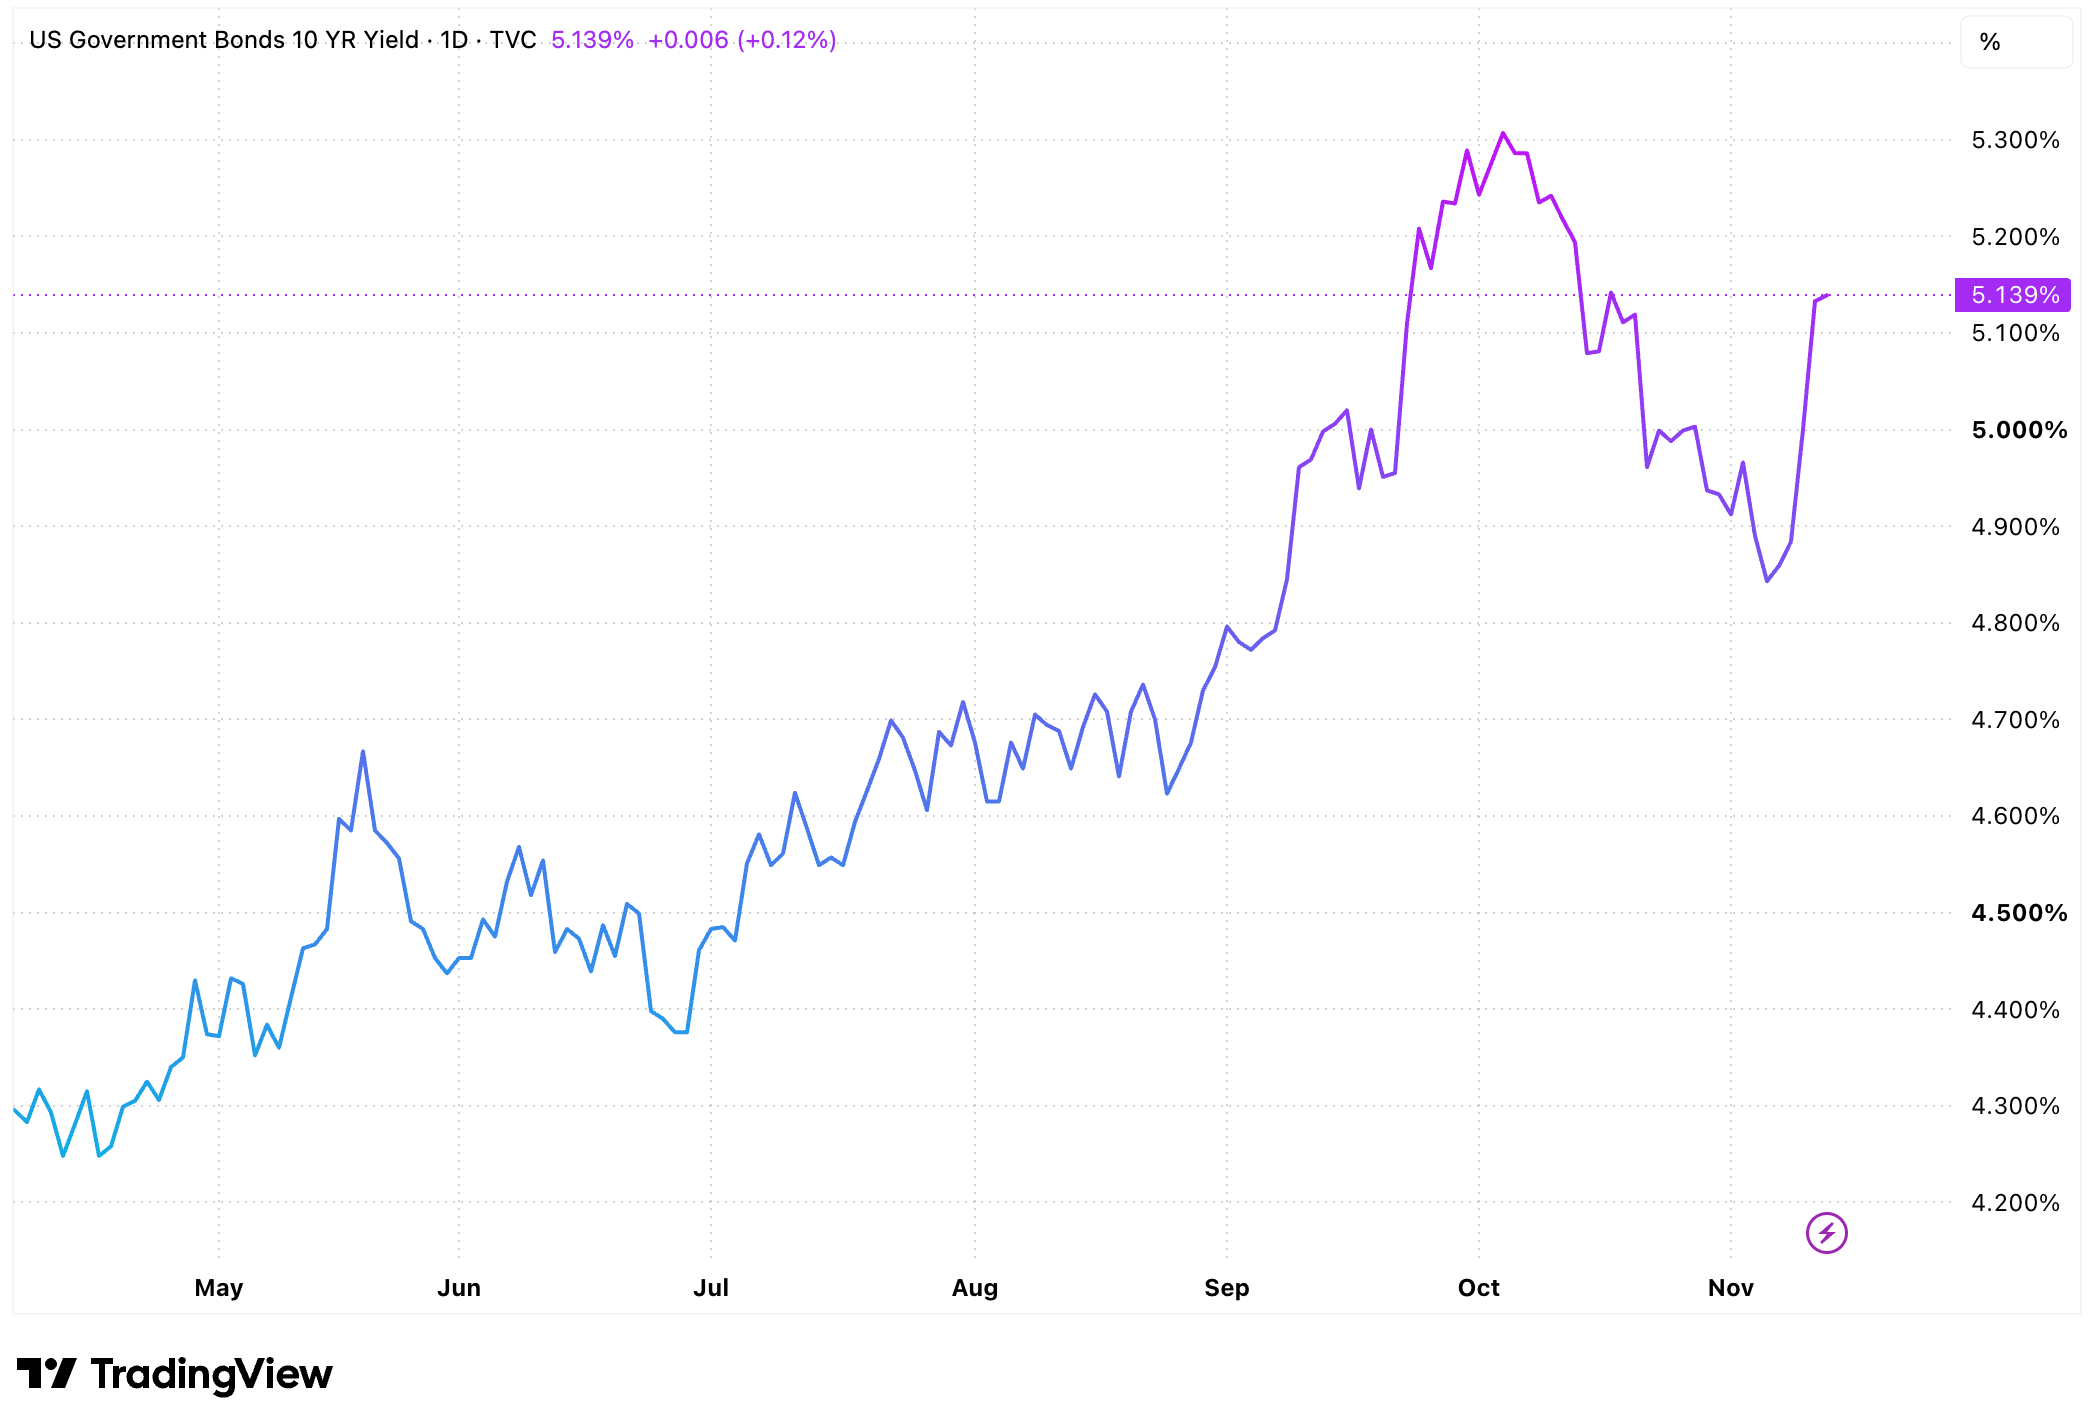
Sentiment improved by a notch. The VIX fell 24.7% from 25.64 to 19.30, back below 20, and the Fear & Greed Index rose from 22 to 39, moving from "Extreme Fear" to "Fear"[3]. Bonds moved the other way: the 10-year Treasury yield jumped roughly 29 bp, from 4.86% to 5.15% (market close), its largest weekly increase since April 2025[2]. Gold futures lost 4–5% as the dollar strengthened[2][3].
This week, Nvidia's earnings and Anthropic's IPO set the new benchmark for the AI trade.
Nvidia reports third-quarter results after the close on Tuesday, Nov. 17. Revenue is expected at $109.5 billion, and options pricing implies a move of about 9% in either direction by the end of the week[1]. On Wednesday, Nov. 18, the minutes of the October FOMC meeting are released and Anthropic is set to price its IPO, with trading on the Nasdaq under the ticker "ANT" scheduled for Thursday, Nov. 19. The $70–78 price range implies a valuation of $1.3 trillion to $1.45 trillion[6]. October retail sales (Nov. 17) and Walmart's results (Nov. 19) will gauge consumer resilience[6].
▲ Bull Case
If interim CEO Kress reaffirms growth guidance and the company's stance on customer financing, relief that the leadership gap won't become an earnings gap could spread. A smooth Anthropic debut would let a listed frontier lab raise capital directly in public markets, weakening the AI ecosystem's reliance on Nvidia's financial backing[3].
▼ Bear Case
If Nvidia flags further executive departures, H200-related write-downs or litigation costs, selling could spread across the AI supply chain[6]. Momentum behind tighter US chip export controls on China is another variable[3]. A further rise in the 10-year yield could renew pressure on growth-stock valuations.
Positioning Takeaways
Last week's rebound started from extremely light positioning. With trend-following CTA funds' equity exposure cut to the 8th percentile[3], direction can flip on a single event. Reviewing single-stock concentration and rate-sensitive exposure around the earnings release looks like a prudent approach.
Key Charts
Fig 1: Nvidia (NVDA) — Down 13% in the Week of Huang's Resignation, Sixth Straight Weekly Loss
source: tradingview.com
Fig 2: US 10-Year Treasury Yield — 4.86% to 5.15%, Largest Weekly Rise Since April 2025
source: tradingview.com
Investment Theme Spotlight
Parking Cash as Rate Hikes Resume: Ultra-Short and Floating-Rate Treasuries
The faster the hiking path, the more short-maturity and rate-linked Treasuries cut the cost of waiting.
Fed funds futures fully price a December hike, and cumulative tightening expected by the end of 2027 rose from 46 bp to 88 bp in a single week[3]. In this environment long bonds swing sharply, while ultra-short Treasuries pass rate hikes through to yields quickly with little price movement. That is why they are cited as a place to park cash ahead of events with two-sided outcomes.
Related ETFs:
- SGOV (iShares 0-3 Month Treasury Bond ETF): Holds Treasuries maturing in three months or less, so price sensitivity to rate moves is very low.
- USFR (WisdomTree Floating Rate Treasury Fund): Holds US Treasury floating-rate notes, so rising short-term rates feed through to income.
Risk factors: If the Fed pauses or pivots to cuts, yields fall with it. Opportunity cost rises in strong equity rallies, and KRW-based investors must also weigh currency risk.
Macro Dashboard
Key Changes Last Week
| Indicator | Level | Change | Takeaway |
|---|---|---|---|
| S&P 500 | 7,561.67 | 7,376.86 → 7,561.67 (+2.51%) | First weekly gain in five weeks |
| Nasdaq Composite | 25,136.27 | 24,579.42 → 25,136.27 (+2.27%) | Four-week losing streak snapped |
| Dow Jones | 52,347.55 | 51,285.73 → 52,347.55 (+2.07%) | All 11 sectors higher |
| KOSPI | 5,290.53 | 5,059.69 → 5,290.53 (+4.56%) | Rebound from nine-month low on Nov. 9 |
| KOSDAQ | 699.66 | 644.27 → 699.66 (+8.60%) | Oversold bounce |
| US 10-Year Treasury | 5.15% | 4.86% → 5.15% (+29 bp) | Hot CPI, hawkish Fed speakers |
| VIX | 19.30 | 25.64 → 19.30 (-24.7%) | Back below 20 |
| Fear & Greed | 39 (Fear) [3] | 22 → 39 | Out of Extreme Fear |
| WTI Crude (Dec) | $88.56 | $90.83 → $88.56 (-2.5%) | Softer amid higher rates |
| USD/KRW | 1,336.7 | 1,356.6 → 1,336.7 (Seoul onshore day-session close) | Won stronger on the week; +6.0 on Friday |
Events to Watch This Week
✔︎ Nvidia Q3 earnings, US October retail sales (Nov. 17): Guidance under the interim CEO and consumer strength
✔︎ October FOMC minutes, Anthropic IPO pricing (Nov. 18): Debate over the size of a December hike and the price of a mega AI listing
✔︎ Anthropic Nasdaq debut, Walmart earnings (Nov. 19): First-day demand and signs of consumer slowdown
✔︎ University of Michigan consumer sentiment, final (Nov. 20): Direction of 1-year inflation expectations (prior 4.3%)[6]
Sources
Market data: exchange closing prices, 10-year Treasury market close, NYMEX settlement, Seoul FX market day-session close
[1] Investopedia (via Yahoo Finance), Markets News, Nov. 13, 2026: S&P 500, Nasdaq Fall as Nvidia, Other Tech Stocks Sink; Major Indexes Post Weekly Gains — https://finance.yahoo.com/markets/stocks/articles/stock-market-today-futures-tick-133734502.html (Nvidia revenue estimate per Visible Alpha; implied options move calculated by Investopedia)
[2] Investrade (Hammerstone Markets), Market Review: November 13, 2026 — https://investrade.com/market-review-november-13-2026/
[3] Atrani Capital (Igor Rotor, CFA), Week #46 — Market Update for November 9-13, 2026 — https://atranicapital.substack.com/p/week-46-market-update-for-november-8a7 (CPI consensus per Bloomberg; Fear & Greed refers to the CNN index)
[4] KPMG, October inflation cinches December rate hike — https://kpmg.com/us/en/articles/2026/october-2026-cpi.html (year-over-year figure is KPMG's interpolated estimate)
[5] Financial News (파이낸셜뉴스), KOSPI hits 5,500 then closes at 5,290.53; foreigners net sell KRW 703.4 billion — https://www.fnnews.com/news/202611131625181132 (foreign net selling per KB Securities 3:30 p.m. tally)
[6] Yahoo Finance, Nvidia's first post-Jensen earnings and Anthropic's IPO: What to watch this week — https://finance.yahoo.com/markets/article/nvidias-first-post-jensen-earnings-and-anthropics-ipo-what-to-watch-this-week-110000732.html
※ This article was written based on the analysis of generative AI.
※ This investment market report is prepared for informational purposes only and should not be interpreted as a solicitation to buy or sell any specific investment product or as investment advice. The final investment decision and the resulting liability rest solely with the investor.


