


"The Blue Wave Takes Aim at AI Infrastructure — Chips Lose 12% in a Day, KOSPI Sheds 11.7% in a Week"
Democrats' capture of Congress in the midterms sparked fears that the AI data-center buildout could slow, sending the Nasdaq to a fourth straight weekly loss and dragging Korea's KOSPI to the edge of 5,000 amid a trading halt. This week, October CPI and CoreWeave's earnings put December rate-hike bets and AI sentiment back to the test.
Last week, the election rewrote the discount rate on AI infrastructure.
Major Index Moves
The S&P 500 fell 2.68% on the week, from 7,580.07 to 7,376.86. The Nasdaq Composite lost 3.37% to 24,579.42, and the Dow slipped 0.94% to 51,285.73 (weekly changes calculated from prior Friday closes). A post-election relief rally lifted the S&P 500 to 7,688.62 on Wednesday, but Thursday erased it all: the index fell 4.4% in a single session, the Nasdaq 5.5%, and the Philadelphia Semiconductor Index (SOX) plunged 12.25%.
Two triggers converged. Beyond Democrats taking both chambers, candidates campaigning on moratoriums for new data centers won in Texas and Georgia, and Qualcomm sank 9.5% the same day after smartphone-chip sales missed estimates[1]. Susquehanna estimated that roughly 60GW of the 148GW of AI-training data-center capacity planned for 2025–2030 is at risk of permitting delays[2]. On Friday, October nonfarm payrolls rose 165,000, far above expectations of about 60,000, and unemployment eased to 4.1%[3]. CME FedWatch odds of a December hike jumped from 67% to 80% overnight[4].
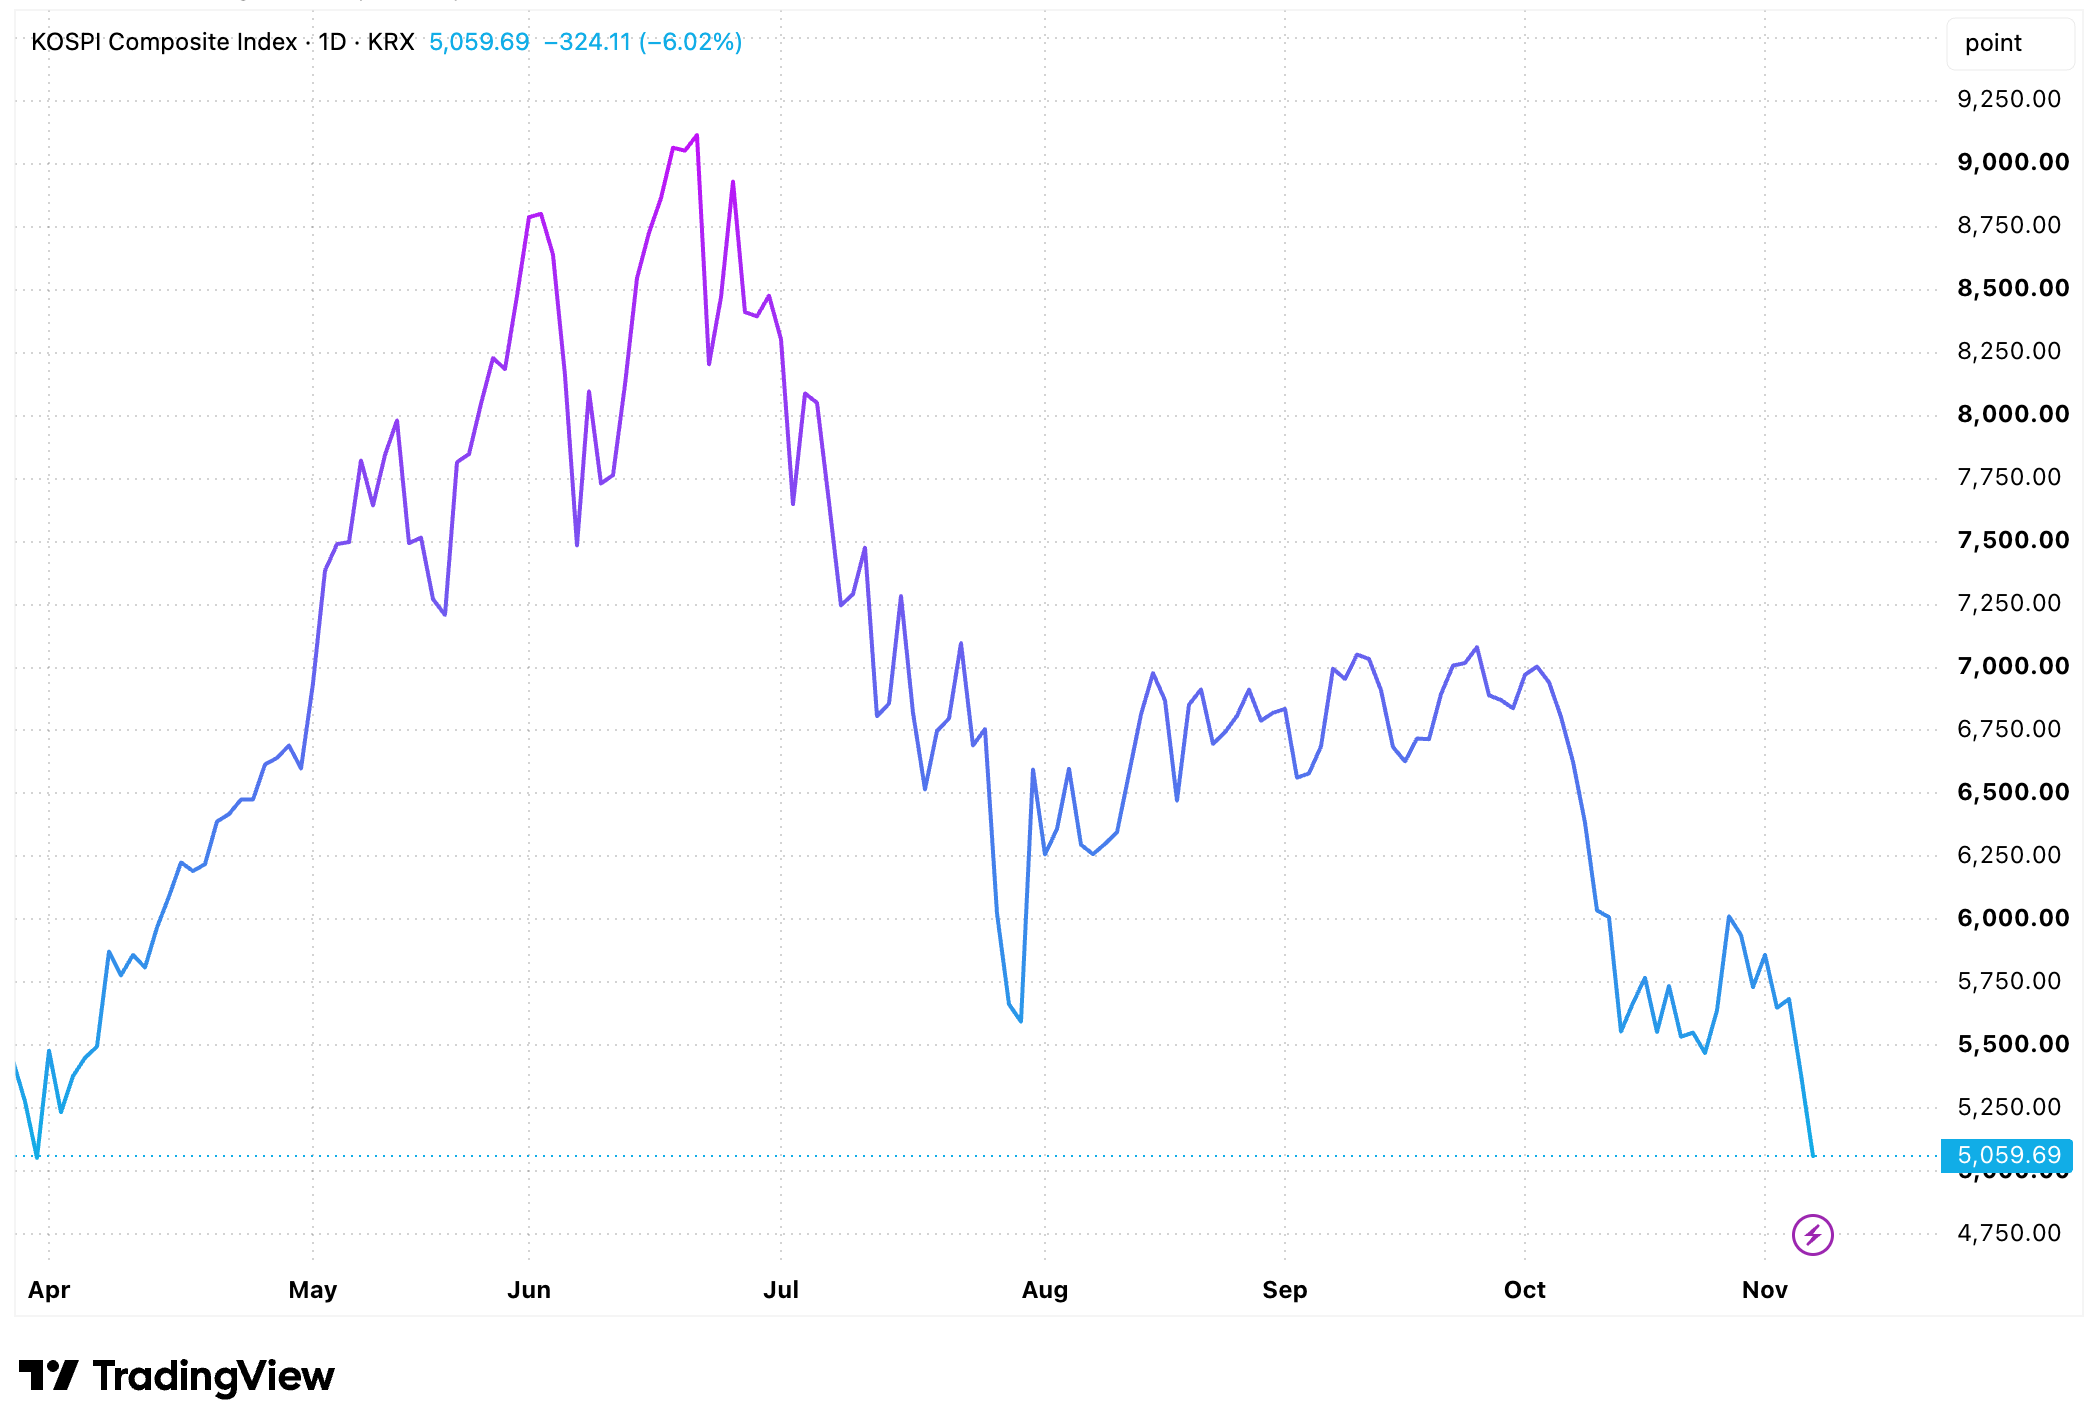
Korea absorbed the shock all at once because of the time difference. The KOSPI fell 5.28% on Thursday and 6.02% on Friday, dropping 11.71% for the week from 5,730.74 to 5,059.69. On Friday morning it broke below 5,000 intraday for the first time since February, triggering a market-wide circuit breaker. Foreign investors sold a net 6.16 trillion won ($4.5 billion) over the two sessions[4], and SK Hynix lost 10.44% on Friday alone.
Technical Analysis
The Nasdaq 100 is now 11.9% below its October 6 record, confirming a technical correction. The Nasdaq Composite sits below its 52-week moving average (about 24,679), while the S&P 500 and Dow remain above rising 52-week lines[5]. First support for the S&P 500 is cited at 7,314, with the 52-week average near 7,220[5]. The VIX spiked to 28.18 on Thursday before closing the week at 25.64, up 32%, and the Fear & Greed Index slid to 22, deep in "extreme fear"[6].
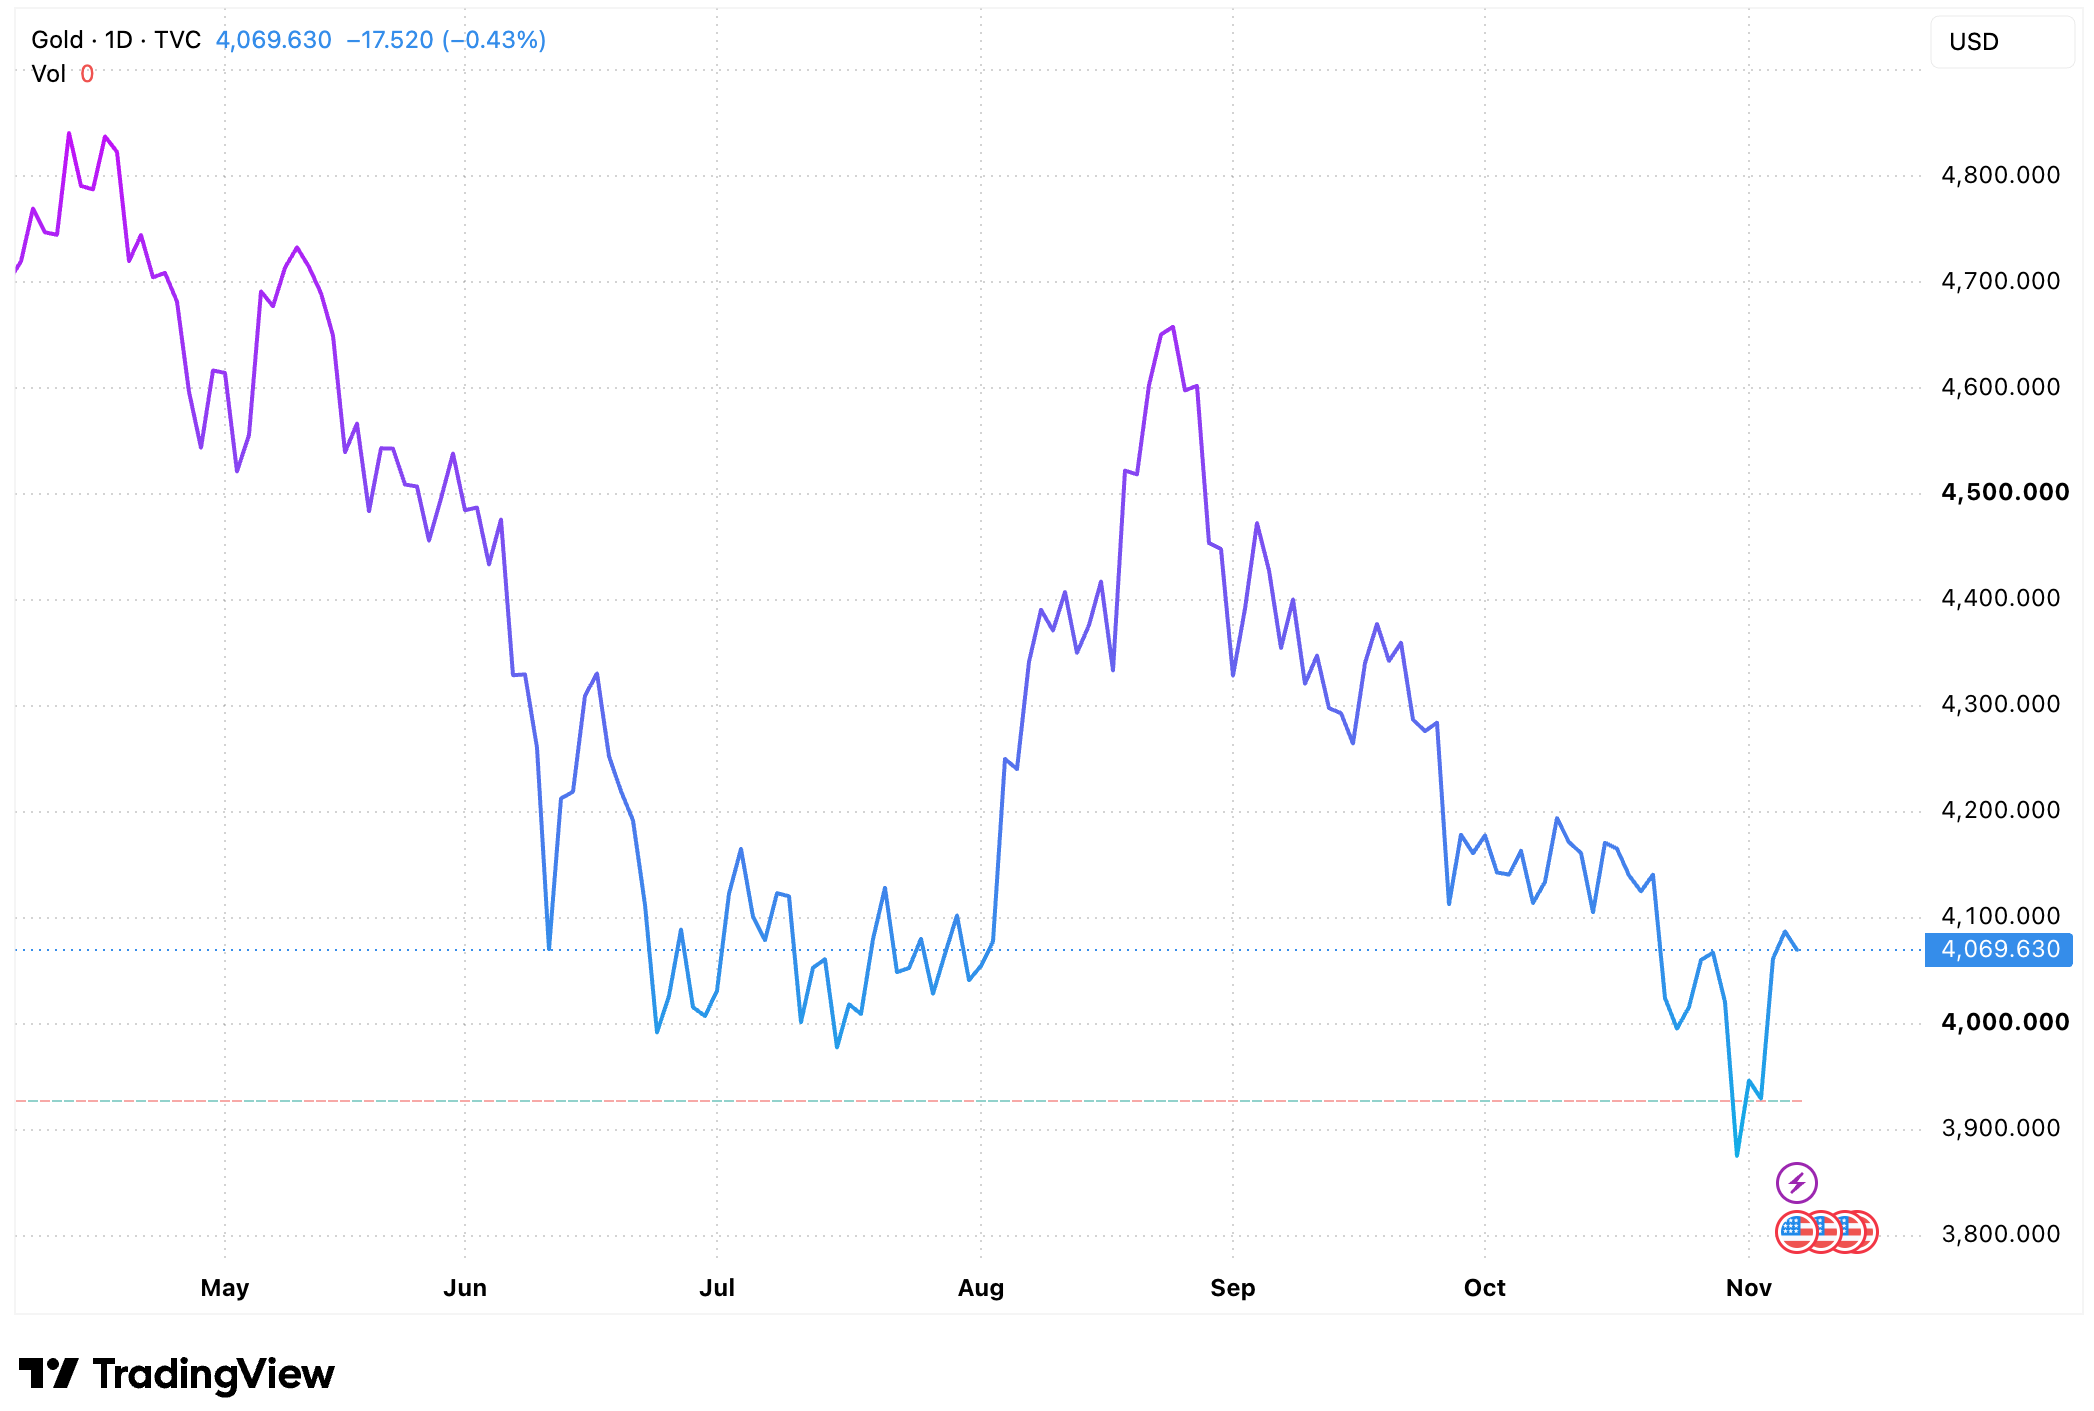
Money rotated into havens. The 10-year Treasury yield fell 8 basis points to 4.86% from 4.94% (market close basis), and spot gold climbed 5.2%, on track for its best week since August[2]. WTI December crude moved the other way, sliding 12.8% from $104.12 to $90.83 as Republican losses raised hopes of de-escalation in the war with Iran[2].
This week, CPI and CoreWeave test both rates and AI's funding pipeline.
October CPI on Tuesday (Nov. 10) is expected to rise 0.3% month over month, with core at 0.2%, followed by PPI on Friday (Nov. 13)[5]. CoreWeave reports after Tuesday's close, with Cisco and Applied Materials on Thursday (Nov. 12). Heavily indebted CoreWeave sits at the center of data-center financing worries, making it the first real test of whether AI stocks can rebound[5].
▲ Bull Case
A CPI print in line with forecasts could lower December hike odds and give tech room to breathe. If CoreWeave defends its financing plans, the view that regulatory risk has been overpriced would gain traction. Korean chipmakers' statements that no customer orders have been canceled also support a recovery[4].
▼ Bear Case
A hot CPI, combined with strong payrolls, could cement a December hike. If CoreWeave signals funding strain, selling could spread again across the data-center supply chain, putting the S&P 500's 7,300 support level back in play.
Positioning Takeaways
Last week's decline priced in a policy variable — permitting delays — more than a collapse in AI demand itself. With volatility elevated, investors may want to review leverage first and diversify across assets with different policy sensitivities.
Key Charts
Fig 1: KOSPI — Down 11.71% on the Week, Battling for 5,000 After a Circuit Breaker
source: tradingview.com
Fig 2: Spot Gold — Up 5.2%, Best Week Since August
source: tradingview.com
Investment Theme Spotlight
Gold as a Hedge Against Policy Uncertainty
While equities digested policy risk, gold absorbed both falling yields and safe-haven demand.
Spot gold rose 5.2% last week as the 10-year yield fell for a fifth straight week[2]. A non-yielding asset, gold becomes relatively more attractive as rates decline, and it moved opposite to stocks during the tech rout, acting as a portfolio shock absorber. Still, gold futures slipped 0.94% on Friday as strong jobs data lifted the dollar and yields[2].
Related ETFs:
- GLD (SPDR Gold Shares): The flagship physically backed gold ETF, with the deepest liquidity in the category.
- IAU (iShares Gold Trust): Also physically backed, but with a lower expense ratio that favors long-term holders.
Risk factors: A hot CPI that boosts December hike bets could push the dollar and yields higher and knock gold back. Gold pays no income, so the opportunity cost of long-term holding should also be weighed.
Macro Dashboard
Key Changes Last Week
| Indicator | Level | Change | Takeaway |
|---|---|---|---|
| S&P 500 | 7,376.86 | 7,580.07 → 7,376.86 (-2.68%) | Thursday -4.4%, biggest daily drop since April 2025 |
| Nasdaq Composite | 24,579.42 | 25,437.00 → 24,579.42 (-3.37%) | Fourth weekly loss, below 52-week average |
| Dow Jones | 51,285.73 | 51,770.31 → 51,285.73 (-0.94%) | Relative outperformer |
| KOSPI | 5,059.69 | 5,730.74 → 5,059.69 (-11.71%) | Circuit breaker on Nov. 6, foreign selling |
| KOSDAQ | 644.27 | 724.38 → 644.27 (-11.06%) | Two straight days of 5%+ losses |
| US 10-Year Treasury | 4.86% | 4.94% → 4.86% (-8bp) | Haven demand, fifth weekly decline |
| VIX | 25.64 | 19.42 → 25.64 (+32%) | Spiked to 28.18 on Thursday |
| Fear & Greed | 22 (extreme fear) [6] | 26 → 22 | Fear deepening |
| WTI Crude (Dec.) | $90.83 | $104.12 → $90.83 (-12.8%) | Iran de-escalation hopes |
| USD/KRW | 1,356.6 | 1,334.3 → 1,356.6 (Seoul daytime close) | Won weakens on foreign outflows |
Events to Watch This Week
✔︎ US October CPI, CoreWeave earnings (Nov. 10): December hike odds and AI data-center financing concerns
✔︎ Cisco and Applied Materials earnings (Nov. 12): Networking and chip-equipment spending
✔︎ US October PPI (Nov. 13): Whether producer prices cool after September's 1.3% jump
✔︎ Fed speakers (Nov. 9–13): Strength of hike signals ahead of the Dec. 8–9 FOMC
Sources
Market data: exchange closes, 10-year Treasury market close, NYMEX settlement, Seoul FX daytime close
[1] Reuters (via Yahoo Finance), Deep chip selloff drags global stocks lower on AI spending concerns — https://finance.yahoo.com/energy/articles/oil-data-centre-stocks-sink-023443660.html
[2] Investrade (Hammerstone Markets), Market Review: November 06, 2026 — https://investrade.com/market-review-november-06-2026/ (includes Susquehanna data-center analysis and weekly gold, oil and Treasury moves)
[3] The Closing Print, Post-Market & Weekly Summary – Nov 6, 2026 — https://www.theclosingprint.net/2026/11/post-market-and-weekly-summary-2026-11-06/ (payroll consensus varied by outlet, roughly 59,000–65,000)
[4] ISSUE ON, 코스피 한 주 11.7% 급락…서킷브레이커 속 외국인 이틀간 6조원 매도 — https://www.issueon.co.kr/news/articleView.html?idxno=14333 (foreign net selling per Korea Exchange tally)
[5] FXEmpire, The Week Ahead: CPI and Tech Earnings Test a Fragile Stock Market — https://www.fxempire.com/forecasts/article/the-week-ahead-cpi-and-tech-earnings-test-a-fragile-stock-market-1643118
[6] FinHacker, Fear and Greed Index: Historical Data & Chart (CNN Fear & Greed, Nov. 6 reading) — https://www.finhacker.cz/en/fear-and-greed-index-historical-data-and-chart/
※ This article was written based on the analysis of generative AI.
※ This investment market report is prepared for informational purposes only and should not be interpreted as a solicitation to buy or sell any specific investment product or as investment advice. The final investment decision and the resulting liability rest solely with the investor.


